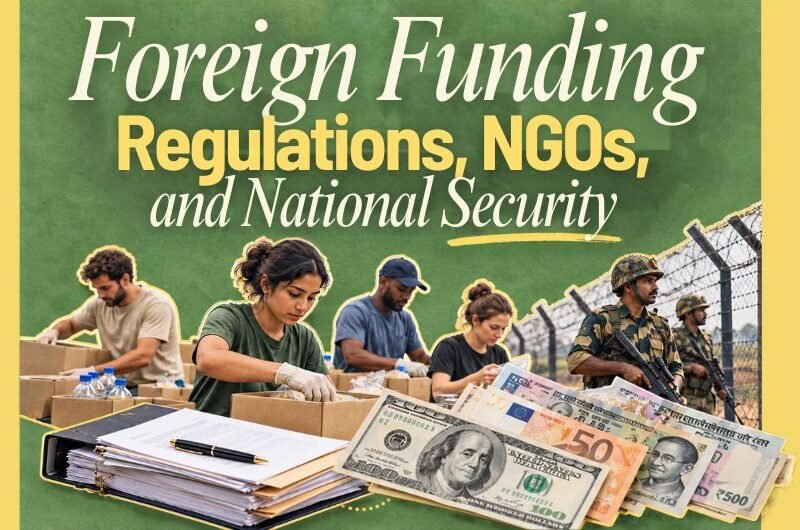
Foreign Funding Regulations, NGOs, and National Security
1. Evolution of Foreign Funding Regulations
The FCRA framework has progressively introduced stricter requirements concerning financial transactions, organisational accountability, permitted activities and the management of foreign-funded assets.
| Feature | FCRA, 2010 | FCRA Amendment, 2020 | FCRA Rules and Proposed Amendments, 2026 |
|---|---|---|---|
| Banking Channel | Foreign contributions could be received through designated bank accounts, subject to reporting requirements. | Required foreign contributions to be received through an FCRA account at the State Bank of India, New Delhi Main Branch. | Continued the designated banking arrangement and strengthened reporting of foreign contributions and their utilisation. |
| Fund Sharing | Permitted transfers of foreign contributions to other eligible FCRA-registered entities. | Prohibited onward transfers of foreign contributions to other persons or organisations. | Continued the restriction while introducing closer monitoring of approved activities and geographical areas of operation. |
| Administrative Expenses | Administrative expenditure was limited to 50% of foreign contributions received. | Reduced the maximum administrative expenditure to 20%. | Retained the 20% ceiling alongside additional compliance and disclosure requirements. |
| Identity and Leadership | Required organisational registration and disclosure of relevant office-bearers. | Introduced Aadhaar identification requirements for specified Indian office-bearers and passport identification for foreign nationals. | Defined key functionaries, including directors, trustees, partners and other responsible officers, with restrictions concerning foreign nationals in such positions. |
| Registration Scope | Provided five-year registration for organisations undertaking cultural, economic, educational, religious or social programmes. | Retained five-year registration and strengthened compliance requirements. | Required organisations to specify their approved purposes and States/UTs of operation. Additional fees apply for specified purposes and geographical areas. |
| Activity Requirements | Registration and renewal were subject to prescribed conditions and compliance requirements. | Strengthened government scrutiny of registration and renewal. | The 2026 Rules introduced a requirement to demonstrate utilisation of at least ₹10 lakh in foreign contributions during the preceding two financial years as evidence of reasonable activity. |
| Asset Management | Provided for vesting of foreign-funded assets in specified circumstances involving cancellation or surrender. | Extended the permissible suspension period of FCRA registration to a maximum of 360 days. | The 2026 Amendment Bill proposes a Designated Authority to supervise and manage foreign-funded assets following cancellation, surrender or cessation of registration. |
2. National Security and Regulation of Foreign Contributions
Regulation of foreign contributions seeks to prevent the misuse of external financial resources for activities that may affect
national security, public order, sovereignty and democratic institutions.
1
Concerns have been raised about the potential use of foreign funding to influence organised opposition to strategic infrastructure, energy and development projects. Controversies involving projects such as the Kudankulam Nuclear Power Plant have highlighted the need to distinguish legitimate public protest from unlawful external financial influence.
2
Undisclosed foreign funding may be used to influence domestic political activities, electoral processes or public policy. The FCRA therefore prohibits specified categories, including election candidates, legislators, political parties, judges and certain news organisations, from accepting foreign contributions.
3
Inadequately monitored international financial transfers may create opportunities for diversion of resources towards extremist activities, unlawful organisations or prohibited financial transactions. Banking controls, identification requirements and financial disclosures are intended to reduce these risks.
4
The FCRA Amendment Rules, 2026 specify permissible purposes within the religious category and exclude proselytisation from specified activities eligible for foreign funding. The framework seeks to distinguish permitted religious and charitable activity from prohibited use of foreign contributions.
3. Implications for Civil Society Organisations
The FCRA framework involves balancing financial transparency and national security requirements with the independence and functioning of voluntary organisations.
A. Benefits of Regulation
The designated SBI banking arrangement, reporting requirements and disclosure of foreign funding sources improve traceability of financial transactions and reduce opportunities for undisclosed transfers.
Restrictions on foreign contributions to political actors and specified institutions seek to prevent external financial influence over domestic political processes and public decision-making.
Registration, renewal, annual reporting and financial scrutiny help identify organisations that are inactive, non-compliant or involved in activities outside their approved purposes.
B. Concerns Regarding Regulation
Impact on Grassroots Organisations:
The prohibition on onward transfers of foreign contributions can affect smaller rural and community-based organisations that previously depended on financial assistance from larger registered NGOs.
Restrictions on Civil Society Activities:
Broad statutory expressions, including activities considered detrimental to the public interest, may create concerns regarding administrative discretion, regulatory uncertainty and the independence of organisations working in fields such as human rights and civil liberties.
Increasing Compliance Burden:
Requirements concerning approved activities, geographical areas, financial disclosures and organisational details increase administrative responsibilities. Smaller organisations may face difficulties in maintaining compliance while continuing community-level programmes.
Management of Foreign-Funded Assets:
The proposed 2026 framework concerning vesting and management of assets has raised questions about treatment of organisations whose registrations expire, are cancelled or are not renewed.
4. Measures to Balance Regulation and Civil Society Autonomy
An effective regulatory framework should ensure transparency and national security while preserving the legitimate activities of civil society organisations.
1
Clear Criteria for Regulatory Action
2
Strengthening Grievance Redressal
3
Proportionate Compliance Requirements
proportionate regulation, procedural safeguards and clearly defined compliance requirements
are necessary to preserve the legitimate role of civil society organisations in social development, public participation and democratic governance.
Must Know Terms
1. Foreign Contribution (Regulation) Act (FCRA)
A legislative framework governing the acceptance and utilisation of foreign contributions by NGOs and other eligible entities in India. Administered by the Ministry of Home Affairs, it aims to ensure financial transparency, accountability and protection of national security.
2. Designated FCRA Bank Account
A mandatory banking arrangement introduced through the FCRA Amendment Act, 2020, requiring organisations to receive foreign contributions through a designated account at the State Bank of India, New Delhi Main Branch. It facilitates financial monitoring and transaction traceability.
3. Prohibition on Sub-Granting
A restriction introduced by the FCRA Amendment Act, 2020, prohibiting recipients of foreign contributions from transferring such funds to other persons or organisations, including FCRA-registered NGOs. It aims to prevent unmonitored financial transfers but may affect smaller grassroots organisations.
4. Administrative Expenditure Ceiling
A statutory restriction limiting the proportion of foreign contributions that organisations may spend on administrative expenses. The FCRA Amendment Act, 2020, reduced the permissible ceiling from 50% to 20%, subject to statutory exceptions and government approval.
5. FCRA Registration and Renewal
A regulatory mechanism requiring eligible organisations to obtain registration or prior permission before accepting foreign contributions. FCRA registration is generally valid for five years and requires periodic renewal, financial reporting and compliance with prescribed conditions.
6. Designated Authority
An institutional mechanism proposed under the FCRA Amendment Bill, 2026, for supervising and managing foreign-funded assets in specified circumstances involving cancellation, surrender or cessation of registration. It is a proposed legislative provision, not an established mechanism under the Bill.
Multiple-Choice Questions
1. With reference to the evolution of the Foreign Contribution (Regulation) Act (FCRA), consider the following statements:
Which of the statements given above are correct?
2. Match List I with List II:
Select the correct answer using the code given below:
3. Consider the following Assertion (A) and Reason (R):
Assertion (A):
The prohibition on onward transfers of foreign contributions may adversely affect smaller grassroots organisations.
Reason (R):
Many rural and community-based organisations previously depended on financial support transferred by larger FCRA-registered organisations.
Select the correct answer:
4. With reference to the FCRA framework, consider the following statements:
Which of the statements given above are correct?
5. With reference to restrictions on foreign contributions under the FCRA, consider the following categories:
Which of the above categories are subject to the specified statutory prohibitions on receiving foreign contributions?
6. Match List I with List II:
Select the correct answer using the code given below:
7. Consider the following statements regarding FCRA registration and financial regulation:
How many of the above statements are correct?
8. Consider the following Assertion (A) and Reason (R):
Assertion (A):
Increasing regulatory compliance requirements may reduce the resources available to smaller NGOs for community-level programmes.
Reason (R):
Requirements relating to financial reporting, approved activities, geographical areas and organisational disclosures may increase administrative responsibilities.
Select the correct answer:
9. With reference to the management of foreign-funded assets under the FCRA framework, consider the following statements:
Which of the statements given above are correct?
10. With reference to national security considerations in the regulation of foreign contributions, consider the following statements:
Which of the statements given above are correct?
11. Consider the following measures for improving the balance between FCRA regulation and civil society autonomy:
Which of the above measures are consistent with the proposed regulatory reforms?
12. Consider the following Assertion (A) and Reason (R):
Assertion (A):
The Designated Authority for managing foreign-funded assets should be distinguished from the regulatory mechanisms already established under the FCRA.
Reason (R):
The Designated Authority for supervising and managing such assets was proposed under the FCRA Amendment Bill, 2026, rather than being an already established institution under that Bill.
Select the correct answer:
13. Match List I with List II:
Select the correct answer using the code given below:
14. Consider the following statements concerning the FCRA framework:
How many of the above statements are correct?
15. Which one of the following approaches would most appropriately reconcile the objectives of national security, financial accountability and civil society autonomy under the FCRA framework?

0 comment